Medicare is the federal health insurance program for people 65 and older and for some younger people with disabilities or end-stage kidney disease. It has four parts: Part A for hospital care, Part B for doctors and outpatient care, Part C for private Medicare Advantage plans, and Part D for prescription drugs.
New to Medicare?
See What It Costs to Fill Medicare’s Gaps in Your ZIP Code
Compare Medicare Supplement prices from several insurance companies side by side.
Rates and plan availability vary by state, age and insurance company.
This page is the map. It shows what each part covers, what each part costs in 2027 using the figures CMS released on November 17, 2026, when you can sign up, and what Original Medicare still leaves you paying. Most people then choose one of two routes to cover those leftover costs, and we explain both.
If you already know you want the route with no networks, our guide to Medicare Supplement plans for 2027 compares the plan letters and prices in detail.
In one sentence
Medicare is federal health insurance for people 65 and older (and some younger people with disabilities), split into Part A for hospitals, Part B for doctors, Part C for private all-in-one plans and Part D for drugs, and in 2027 the standard Part B premium is $209.40 a month.
The Four Parts of Medicare at a Glance
Parts A and B together are called Original Medicare, and the federal government runs them directly. Parts C and D are sold by private insurance companies that contract with Medicare. You can mix the parts in only a few ways, so it helps to see them side by side.
| Part | What it pays for | Main 2027 cost |
|---|---|---|
| Part A (hospital) | Inpatient hospital stays, skilled nursing after a qualifying stay, hospice, some home health care | $0 premium for most people; $1,776 deductible per benefit period |
| Part B (medical) | Doctor visits, outpatient surgery, lab work, imaging, durable equipment, preventive care | $209.40 a month; $292 yearly deductible; then usually 20% |
| Part C (Medicare Advantage) | Replaces how you get A and B through a private plan, usually with a network and drug coverage | Plan premium varies; you still pay the Part B premium |
| Part D (drugs) | Outpatient prescription drugs through a private plan | Plan premium varies; deductible can be no more than $700 |
Source: CMS 2027 Medicare Parts A and B premiums and deductibles fact sheet (November 17, 2026); Part D deductible limit from the CY 2027 Part D announcement.
Easy to miss
Original Medicare has no yearly out-of-pocket limit. The 20% you owe under Part B keeps running no matter how large the bill gets, which is the main reason most people add coverage on top.
Part A in 2027: What a Hospital Stay Costs
About 99% of people pay no premium for Part A because they or a spouse worked and paid Medicare taxes for at least 40 quarters (about 10 years). If you have fewer quarters you can buy Part A: $328 a month with 30 to 39 quarters, or $597 a month with fewer than 30.
A benefit period starts the day you are admitted and ends after you have been out of the hospital or nursing facility for 60 days in a row. That means two separate hospital stays in the same year can mean paying the $1,776 deductible twice. Part A also covers skilled nursing care only after a qualifying inpatient stay, and time spent under observation status does not count toward it.

Agent’s desk
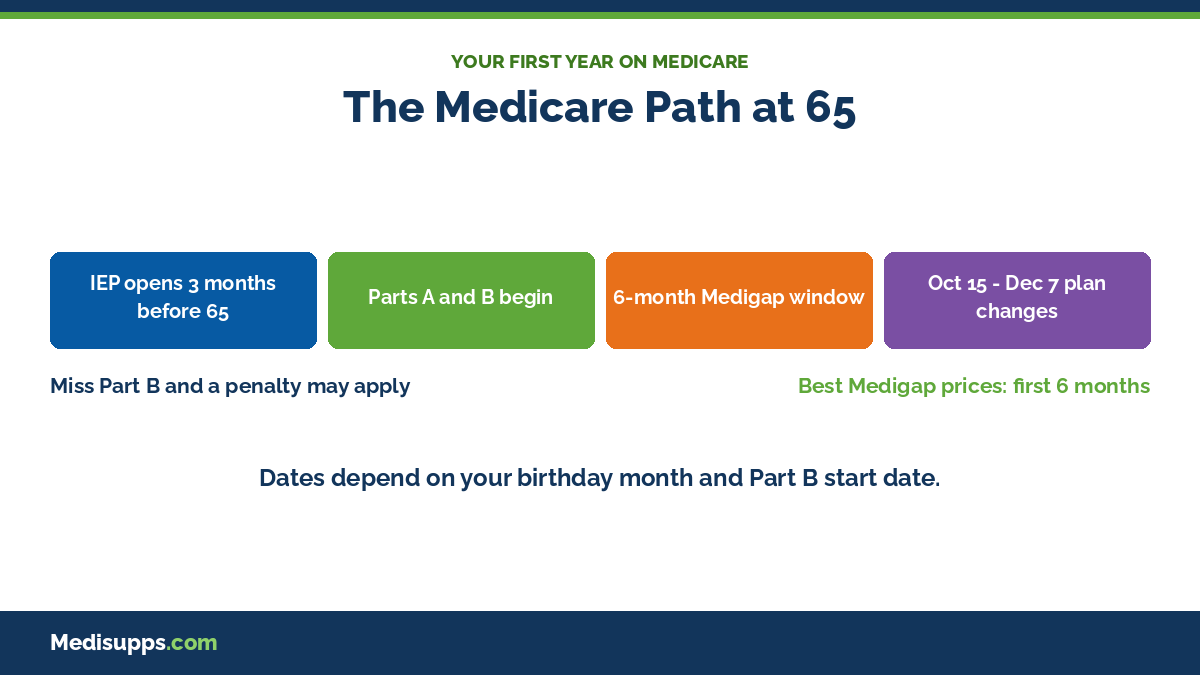
The Part B effective date controls the start of the six-month Medigap open enrollment window. Delaying Part B because of active employer coverage also delays that window, so the guaranteed right to buy any Medigap plan is still there when the job coverage ends.
Russell Noga, Licensed Insurance Agent
Part B in 2027: Premium, Deductible and IRMAA
Most people pay the standard Part B premium of $209.40 a month in 2027, up $6.50 from $202.90 in 2026. The yearly deductible rises to $292. After that, you generally pay 20% of the Medicare-approved amount for covered services.
Higher earners pay more through the income-related monthly adjustment amount, or IRMAA. Social Security uses your tax return from two years earlier, so your 2025 income sets your 2027 premium. If your income dropped after retirement, you can ask Social Security to use the newer figure with form SSA-44.
| 2025 income, single | 2025 income, joint | 2027 Part B monthly premium |
|---|---|---|
| $112,000 or less | $224,000 or less | $209.40 |
| $112,001 to $141,000 | $224,001 to $282,000 | $293.10 |
| $141,001 to $177,000 | $282,001 to $354,000 | $418.80 |
| $177,001 to $212,000 | $354,001 to $424,000 | $544.40 |
Source: CMS 2027 fact sheet. Two higher tiers apply above $212,000 single or $424,000 joint. Part D premiums carry a separate income adjustment.
What Original Medicare Leaves You Paying: A 2027 Example
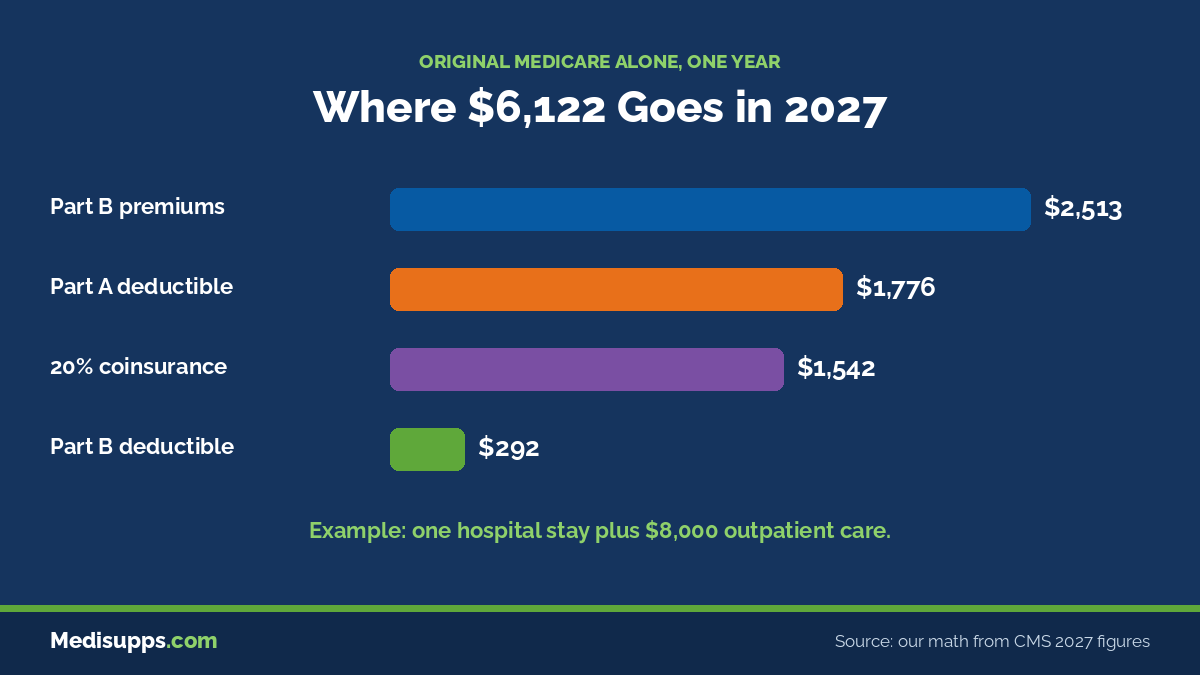
To show why the gaps matter, here is our own worked example using only the official 2027 figures. Picture someone on Original Medicare with no extra coverage who has one hospital admission and $8,000 of Medicare-approved outpatient care during the year, such as tests, a procedure and follow-up visits.
Total for the year
$6,122.40, of which $3,609.60 is cost sharing on top of the premium. A second hospital stay, a longer stay or a larger outpatient bill would push that number higher, because Original Medicare never caps it.
Two Ways to Fill the Gaps
Almost everyone on Medicare picks one of two routes. You cannot use both at once, and the choice you make at 65 can be hard to undo later.
With a Medigap Plan G, the person in the example above would have paid the $292 Part B deductible and nothing more for those covered services, plus the Plan G premium. With a Medicare Advantage plan, the cost depends on that plan’s copays, up to its out-of-pocket maximum.
Medicare Supplement Quotes
Call a Licensed Agent Now
A licensed agent can compare Medigap plans and explain your enrollment dates at no cost.
No obligation to enroll
Medicare Enrollment Periods and Deadlines
| Window | When | What you can do |
|---|---|---|
| Initial Enrollment Period | 7 months: 3 before your 65th birthday month, that month, and 3 after | Sign up for Parts A and B, and join a Part C or Part D plan |
| Medigap open enrollment | 6 months starting the month you are 65+ and have Part B | Buy any Medigap plan sold in your state with no health questions |
| General Enrollment Period | January 1 to March 31 | Sign up for Part B if you missed your first chance; coverage starts the next month |
| Annual Enrollment Period | October 15 to December 7 | Join, switch or drop Medicare Advantage and Part D plans for January 1 |
| Medicare Advantage Open Enrollment | January 1 to March 31 | Make one switch to another Advantage plan or back to Original Medicare |
Special Enrollment Periods also apply, for example when you lose job-based coverage. See our Medicare enrollment guide.
If you are already getting Social Security benefits at 65, you are enrolled in Parts A and B automatically and your card arrives in the mail. Everyone else signs up through Social Security, online or in person.
Late Penalties and Common Mistakes
- ✔Skipping Part B without other qualifying coverage. The penalty is 10% of the standard premium for each full 12-month period you could have had it, and it lasts as long as you have Part B.
- ✔Going without creditable drug coverage for 63 days or more after your first chance to join Part D. That adds a lifetime Part D penalty.
- ✔Assuming retiree or COBRA coverage counts as active work coverage for delaying Part B. It usually does not.
- ✔Waiting past your six-month Medigap window. In most states, insurers can then ask health questions and decline you.
- ✔Picking a plan only on premium. Compare yearly out-of-pocket costs, doctors and drugs.
You can return to this overview any time from the Medisupps.com home page.
Free side-by-side quote
Turning 65 or Leaving Work Coverage? Check Your Options First
Your best Medigap prices come during your first six months on Part B.
Rates and plan availability vary by state, age and insurance company.
Medicare Questions We Hear Most
➤ Is Medicare free at 65?
Part A is free for most people who worked about 10 years. Part B is not: the standard 2027 premium is $209.40 a month, and it is usually deducted from your Social Security check.
➤ What is the difference between Medicare and Medicaid?
Medicare is based on age or disability and is run by the federal government. Medicaid is based on income and assets and is run by each state. Some people qualify for both and are called dual eligible.
➤ Do I have to sign up for Medicare if I am still working?
If you or your spouse have health coverage from active work at an employer with 20 or more employees, you can usually delay Part B without a penalty. Many people still take premium-free Part A. Check with the employer plan first.
➤ Does Medicare cover dental, vision and hearing?
Original Medicare does not cover routine dental care, eye exams for glasses or hearing aids. Many Medicare Advantage plans include some of these benefits, and standalone dental and vision policies are also sold.
➤ Is there a cap on what I pay with Original Medicare?
No. Original Medicare has no yearly out-of-pocket maximum. A Medigap plan or a Medicare Advantage plan’s out-of-pocket limit is what puts a ceiling on your costs.
➤ When does my Medicare card arrive?
If you are already receiving Social Security, your card usually arrives about three months before your 65th birthday. If you apply yourself, it typically arrives a few weeks after your application is approved.
Free Medicare Help
Call a Licensed Agent Now
Get Medigap prices from several insurance companies in a single call.
No obligation to enroll
Medisupps.com is operated by ZRN Health & Financial Services, LLC, a licensed insurance agency based in Austin, Texas. We are not connected with or endorsed by the U.S. government or the federal Medicare program. Premiums are examples only; your rate depends on your age, ZIP code, tobacco use and the insurance company.
Russell Noga is the CEO and Medicare editor of Medisupps.com. His 15 years of experience in the Medicare insurance market includes being a licensed Medicare insurance broker in all 50 states. He is frequently featured as a featured as a keynote Medicare event speaker, has authored hundreds of Medicare content pages, and hosts the very popular Medisupps.com Medicare Youtube channel. His expertise includes Medicare, Medigap insurance, Medicare Advantage plans, and Medicare Part D.