by Russell Noga | Updated October 6th, 2026
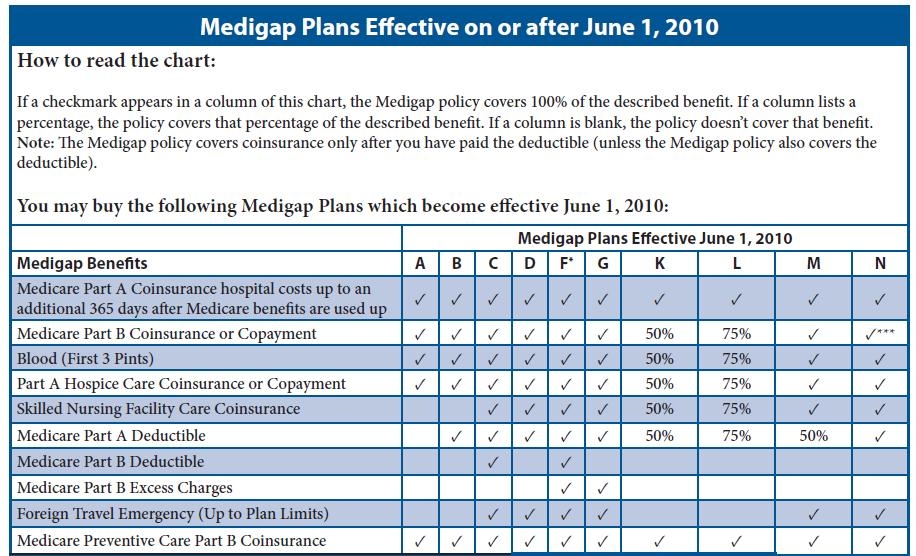
There are 10 different Medigap plans on the Medicare Supplement plans comparison chart for 2027.
The Medicare Supplement comparison chart for 2027 below is an easy way to compare Medicare Supplement plans and benefits side by side.
Every plan letter covers the same benefits no matter which company sells it, but the monthly premiums for the same plan can be very different from one insurance company to the next.
Medicare Supplement Insurance Plans for 2027 - Which Are Best?
Even though there are 10 Medicare Supplement plans on the comparison chart, most people choosing Medicare Supplement plans for 2027 pick from just a few popular options.
The Top Medicare Supplement Plans for 2027 are:
- Medicare Plan G
- Medicare Plan N
- Medicare Plan F (only if eligible for Medicare before January 1, 2020)
- High-deductible Plan G
Compare Medicare Supplement Plans for 2027
This chart might seem a little confusing at first, but it is simple once you know how to read it. Below the chart we break down the most popular Medigap plans so you can see exactly what each one covers.
You will see 10 plans listed, but there are really 12, because Plan G and Plan F each also come in a high-deductible version.
2027 Medicare Costs at a Glance
Medigap benefits do not change from year to year, but the Medicare amounts they help pay do. Medicare announces the 2027 amounts later in the fall. These are the current 2026 figures:
| Medicare cost | 2026 amount |
|---|---|
| Part A hospital deductible (per benefit period) | $1,736 |
| Part B annual deductible | $283 |
| High-deductible Plan G / Plan F deductible | $2,950 |
| Plan K out-of-pocket limit | $8,000 |
| Plan L out-of-pocket limit | $4,000 |
We will update this table with the 2027 amounts as soon as Medicare publishes them.
What is a Medigap Plan?
Medicare Supplement Insurance, also known as Medigap, is a policy designed to supplement Original Medicare (Parts A and B). It covers many of the out-of-pocket costs Original Medicare leaves behind, such as deductibles, copayments and coinsurance. Medigap plans are sold by private insurance companies and work alongside Original Medicare.
The Gaps in Medicare
Original Medicare covers many medical expenses, but not everything. The gaps in coverage can leave Medicare beneficiaries with significant out-of-pocket costs.
These costs add up quickly, especially for people with chronic health conditions or who need frequent care. Medicare Supplement plans are designed to fill these gaps so your costs are predictable.
Who is Eligible for a Medigap Plan?
To buy a Medigap plan, you must be enrolled in both Part A and Part B of Original Medicare and live in the area where the insurance company sells the plan. Most buyers are 65 or older. People under 65 on Medicare due to disability can buy Medigap in some states, depending on state rules.
Medigap plans are not the same as Medicare Advantage plans. Medicare Advantage plans deliver your Medicare benefits through a private plan, while Medigap plans supplement Original Medicare. A Medigap plan cannot be used with a Medicare Advantage plan, so to buy one you need to return to Original Medicare.
Losing Your Medicare Advantage Plan in 2027?
Many Medicare Advantage members are getting non-renewal letters for 2027. If your plan is leaving Medicare or stops serving your area, federal law generally gives you a guaranteed issue right to buy certain Medigap plans, which for most people include Plan G, without medical underwriting.
This right is time-limited and generally ends 63 days after your Medicare Advantage coverage ends. See our full guide to Medicare Supplement Plans 2027, or call 1-888-891-0229 and a licensed agent will check which plans you can get without health questions.
Medicare Part B Deductible
The Part B deductible is the amount you pay each year before Medicare begins to pay for doctor visits and other outpatient care.
For 2026 the annual Medicare Part B deductible is $283. Medicare announces the 2027 amount later in the fall.
Only Plan C and Plan F cover the Part B deductible, and both are limited to people who were eligible for Medicare before January 1, 2020. Their premiums are usually much higher, so in most cases Plan G saves people money even after paying the deductible themselves.
If you are enrolled in both Parts A and B of Original Medicare and want predictable coverage for your out-of-pocket costs, a Medigap plan may be a good option for you.
Compare Plans & Rates
Enter Zip Code
What is the Best Medicare Supplement Plan for 2027?
There is no single “best Medicare Supplement” for everyone. Start with the most popular Medicare Supplement plans below to understand what each one covers, then decide which fits your needs and budget.
Medigap Plan F
Medicare Plan F supplements Original Medicare (Parts A and B) and covers more of the gaps than any other plan, including deductibles, copayments and coinsurance.
Also known as Medigap Plan F, it was considered the best Medicare Supplement for years because it covers 100% of the gaps in Medicare. It is also the highest-priced plan.
What Does Medigap Plan F Cover?
Plan F covers the Part A deductible, which is what you pay before Medicare begins to cover hospital costs, and the Part B deductible, which is what you pay before Medicare begins to cover doctor visits and outpatient care.
Plan F also covers copayments, coinsurance and Part B excess charges for hospital stays, procedures and doctor visits.
Plan F is the most comprehensive Medigap plan. For Medicare-approved care there are no copays, no coinsurance and no costs other than your monthly premium.
Medicare Plan F Cost
The cost of Medigap Plan F depends on several factors, including your age, gender, tobacco use, ZIP code and any household discounts that apply.
Let us compare different insurance companies’ rates so you find the best price for your needs and budget.
Medigap Plan F is not the same as Medicare Advantage. Medicare Advantage plans replace how you get your Original Medicare benefits, while Medigap plans supplement Original Medicare. Medicare Advantage plans often have lower premiums, but you may pay more when you use care, and you usually must use the plan’s network of doctors and hospitals.
Medigap Plan F is a strong option for those who want the most complete coverage for the costs Original Medicare does not pay.
Medicare Plan F Eligibility
*Only people who were eligible for Medicare before January 1, 2020 can enroll in Medigap Plan F.
If you are still on Plan F, check the rates for Plan G using our website. You may be able to save money by switching to Plan G or Plan N.
Medicare Plan G
Medicare Plan G is one of the most popular Medigap plans for 2027 among people new to Medicare, because it offers the most complete coverage available to them. People who became eligible for Medicare on or after January 1, 2020 cannot buy Plan F, which makes Plan G the next best choice for many beneficiaries.
Many people consider Plan G the best Medicare Supplement for the most coverage at a reasonable cost.
Medigap Plan G Coverage
Medigap Plan G covers the Part A deductible, which is what you pay before Medicare begins to cover hospital costs.
The only difference between Plan F and Plan G is that Plan G does not cover the Medicare Part B deductible, the amount you pay each year before Medicare begins to cover doctor visits and outpatient care.
After that deductible, Plan G covers copayments, coinsurance and other out-of-pocket costs for hospital stays, procedures and doctor visits.
Plan G also covers Part B excess charges, which some doctors bill above the Medicare-approved amount. If you see a doctor who charges more than the Medicare-approved amount, Plan G covers the difference.
Cost of Medicare Plan G in 2027
The cost of Medigap Plan G in 2027 depends on the insurance company and where you live. Your age, gender and tobacco use also affect the premium, so compare several companies to find the best price.
Medicare Supplement Plan G is not the same as Medicare Advantage. Medicare Advantage plans replace how you get your Original Medicare benefits, while Medigap plans supplement Original Medicare.
Medicare Advantage plans often have lower premiums, but you may pay more when you use care, and you usually must use the plan’s network.
Medigap Plan G is a strong option in 2027 for those who want comprehensive coverage for the costs Original Medicare does not pay.
Medigap Cost Comparison Chart
The chart above compares the benefits of each Medigap plan letter. It does not compare costs.
Any chart comparing Medigap costs can only show rough examples. The premium you actually pay is likely to be quite different.
Medigap premiums are based on:
- Age
- ZIP code
- Gender
- Tobacco use
- Any household discounts
To see the cost of Medigap plans in your area, enter your ZIP code below for accurate rates on Plan F, G and N. Or call us today at 1-888-891-0229.
Medicare Plan N
Medigap Plan N covers many of the out-of-pocket costs Original Medicare leaves behind, with lower monthly premiums than Plan F or Plan G.
Plan N covers the Part A deductible, hospital coinsurance and most Part B coinsurance. Like Plan G, it does not cover the Part B deductible.
The main difference is that Plan N may require a copayment of up to $20 for some doctor visits and up to $50 for emergency room visits that do not end in admission. These small copays help keep Plan N’s premium lower.

Plan N also does not cover Part B excess charges, which some doctors bill above the Medicare-approved amount. If you see a doctor who charges more than the Medicare-approved amount, you pay the difference.
With Plan N you pay the annual Part B deductible yourself. Other costs that can come up on Plan N are:
- Up to a $20 copay for some doctor visits (telehealth visits do not apply)
- Up to a $50 copay for ER visits if you are not admitted (does not apply to urgent care centers)
- Part B excess charges (rare, and typically low cost)
Medicare Plan N vs Plan G
Plan N and Plan G are similar in many ways. Both cover the Part A deductible and hospital costs, and neither covers the Part B deductible. The difference is that Plan N may require small copays for doctor visits and emergency room visits.
Plan G also covers Part B excess charges, while Plan N does not. If you see a doctor who charges more than the Medicare-approved amount, Plan G covers the difference and Plan N does not.
Cost of Medicare Supplement Plan N in 2027
The cost of Medicare Supplement Plan N in 2027 depends on the insurance company and where you live. Your age, gender and tobacco use also affect the premium, so compare several companies to find the best price.
Medicare Supplement Plan N is a good option in 2027 for people who want solid coverage for the costs Original Medicare does not pay and are comfortable with small copays for doctor and emergency room visits.
Whichever plan looks best, we can answer your questions and compare rates from top insurance companies in your area, so you do not overpay.
Our service is entirely free.
How Does Medicare Supplement Insurance Work?
To enroll in Medicare Supplement insurance, you must have Original Medicare Part A and Part B in place, or be in the process of enrolling.
Medicare is a government health insurance program that covers hospital stays (Part A) and doctor visits and outpatient care (Part B).
Original Medicare covers many medical expenses, but not everything. It does not cover most prescription drugs, and it leaves you paying a share of the cost for hospital stays, procedures and doctor visits.
Why Choose a Medigap Plan?
Medicare Supplement plans are insurance policies sold by private insurance companies. They work alongside Original Medicare and fill the gaps Original Medicare leaves. There are several Medicare Supplement plans, each with its own set of benefits.
How Do Medigap Plans Work?
When you enroll in a Medigap plan, you must also be enrolled in both Parts A and B of Original Medicare. The plan then pays many of the costs Original Medicare does not, such as deductibles, copayments and coinsurance, depending on the plan.
For example, if you are hospitalized, most Medigap plans pay the Part A deductible, the amount you owe before Medicare begins to cover hospital costs. Your plan also helps with coinsurance for your hospital stay and for other procedures and doctor visits.
What Does a Medicare Supplement Plan Cover?
Coverage depends on the plan you choose. Every Medicare Supplement plan covers a core set of basic benefits: Part A hospital coinsurance and extra hospital days after Medicare benefits run out, Part B coinsurance or copayments, the first three pints of blood, and Part A hospice coinsurance. Plans K and L cover some of these at 50% or 75%.
Many plans add more, such as the Part A deductible, skilled nursing coinsurance, Part B excess charges and foreign travel emergency care. The exact coverage of each plan is shown on the comparison chart above.
How Do I Enroll in a Medigap Plan?
To enroll in a Medicare Supplement plan, you must be enrolled in both Parts A and B of Original Medicare and live in the area where the company sells the plan. The best time to enroll is your Medigap Open Enrollment Period, the 6 months starting the month you are 65 or older and enrolled in Part B, or during a guaranteed issue right, because the company cannot turn you down for health reasons.
A Medicare Supplement plan cannot be used with a Medicare Advantage plan, so if you are in Medicare Advantage you need to return to Original Medicare to use one.
How Do I Choose the Right Medicare Supplement Plan?
Choosing the right Medicare Supplement plan takes some thought. Consider your health needs, your budget and the coverage of each plan.
A licensed insurance agent can help you compare plans and enroll in the right policy, and can answer your questions about exactly what each plan covers.
In short, Medicare Supplement insurance works alongside Original Medicare to fill its gaps, giving you predictable coverage for your out-of-pocket costs and helping you save money on your healthcare.
Medicare Supplement Rates in 2027
Medicare Supplement rates are based on several personal factors, so you cannot get an accurate quote without sharing them with an agent.
Each factor carries a different level of risk. For example, premiums for men are usually higher than for women, rates in Florida are higher than in North Carolina, and tobacco users typically pay more.
Medicare Supplement rates are based on:
- Gender
- Age
- Tobacco use
- ZIP code
- Household discounts
How to Get Quotes and Enroll in 2027
Our licensed insurance agents can answer any questions you have about Medicare and Medigap insurance.
We will show you the rates from top companies in your area and help you find the best plan for your needs.
Call 1-888-891-0229 today to get started.
Medicare Supplement Comparison Chart FAQs
How many Medicare Supplement plans are there in 2027?
There are 10 standardized Medigap plans: A, B, C, D, F, G, K, L, M and N. Plan F and Plan G also come in high-deductible versions. Plans C and F are only available to people eligible for Medicare before January 1, 2020.
Do Medicare Supplement plan benefits change in 2027?
No. Medigap benefits are standardized by law, so each plan letter covers the same things in 2027 as in 2026. What changes are the premiums each company charges and the Medicare deductibles the plans help pay.
What is the difference between Plan G and Plan N?
Both cover the Part A deductible and hospital costs, and neither covers the Part B deductible. Plan N may charge up to $20 for some doctor visits and up to $50 for ER visits that do not end in admission, and it does not cover Part B excess charges. In exchange, Plan N usually has a lower premium.
Which Medicare Supplement plans cover the Part B deductible?
Only Plan C and Plan F cover the Part B deductible, and both are only available to people who were eligible for Medicare before January 1, 2020. The Part B deductible is $283 in 2026.
Can I buy a Medigap plan if my Medicare Advantage plan ends in 2027?
Usually, yes. If your Medicare Advantage plan leaves Medicare or stops serving your area, you generally have a guaranteed issue right to buy certain Medigap plans, which for most people include Plan G, without medical underwriting. The right generally ends 63 days after your Medicare Advantage coverage ends.
Russell Noga is the CEO and Medicare editor of Medisupps.com. His 15 years of experience in the Medicare insurance market includes being a licensed Medicare insurance broker in all 50 states. He is frequently featured as a featured as a keynote Medicare event speaker, has authored hundreds of Medicare content pages, and hosts the very popular Medisupps.com Medicare Youtube channel. His expertise includes Medicare, Medigap insurance, Medicare Advantage plans, and Medicare Part D.