Medicare Supplement Plan F pays every out-of-pocket cost Original Medicare leaves for covered services, including the Part B deductible, but only people who were eligible for Medicare before January 1, 2020 can buy it. If you turned 65 on or after that date, Plan F is closed to you and Plan G is the closest option.
Have Plan F today?
Check Whether Plan G Would Cost You Less
Compare Plan F and Plan G premiums from several insurers in your ZIP code.
Rates and plan availability vary by state, age and insurance company.
For about two decades Plan F was the default choice because it meant no bills at all after Medicare. A 2015 federal law changed that by barring new enrollees from plans that pay the Part B deductible. Millions of people still hold Plan F, and many others still qualify to buy it. This page covers what Plan F pays in 2027, exactly who can buy it, the math on keeping it versus moving to Plan G, and what the closed status means for future premiums.
To see how Plan F fits with every other plan letter this year, read our guide to Medicare Supplement plans for 2027.
Straight answer
Medicare Supplement Plan F covers 100% of Medicare-approved costs after Medicare pays, including the $292 Part B deductible in 2027, but it is sold only to people first eligible for Medicare before January 1, 2020; for most people who can choose, Plan G costs less overall.
What Plan F Pays in 2027
Plan F covers the same benefits no matter which company sells it. Here is what it pays using the official 2027 Medicare amounts.
| Cost Medicare leaves you | 2027 amount | Plan F pays |
|---|---|---|
| Part A hospital deductible | $1,776 per benefit period | 100% |
| Hospital days 61-90 | $444 a day | 100% |
| Lifetime reserve days | $888 a day | 100%, plus 365 extra days |
| Skilled nursing days 21-100 | $222 a day | 100% |
| Part B deductible | $292 a year | 100% |
| Part B coinsurance | Usually 20% | 100% |
| Part B excess charges | Up to 15% above Medicare’s rate | 100% |
| Emergency care abroad | Not covered by Medicare | 80% after $250, up to a $50,000 lifetime limit |
Source: CMS 2027 Parts A and B fact sheet (November 17, 2026). Plan F also covers the first three pints of blood and hospice coinsurance.
Like every Medigap plan, Plan F does not cover prescriptions, routine dental or vision care, or long-term custodial care.
Who Can Still Buy Plan F
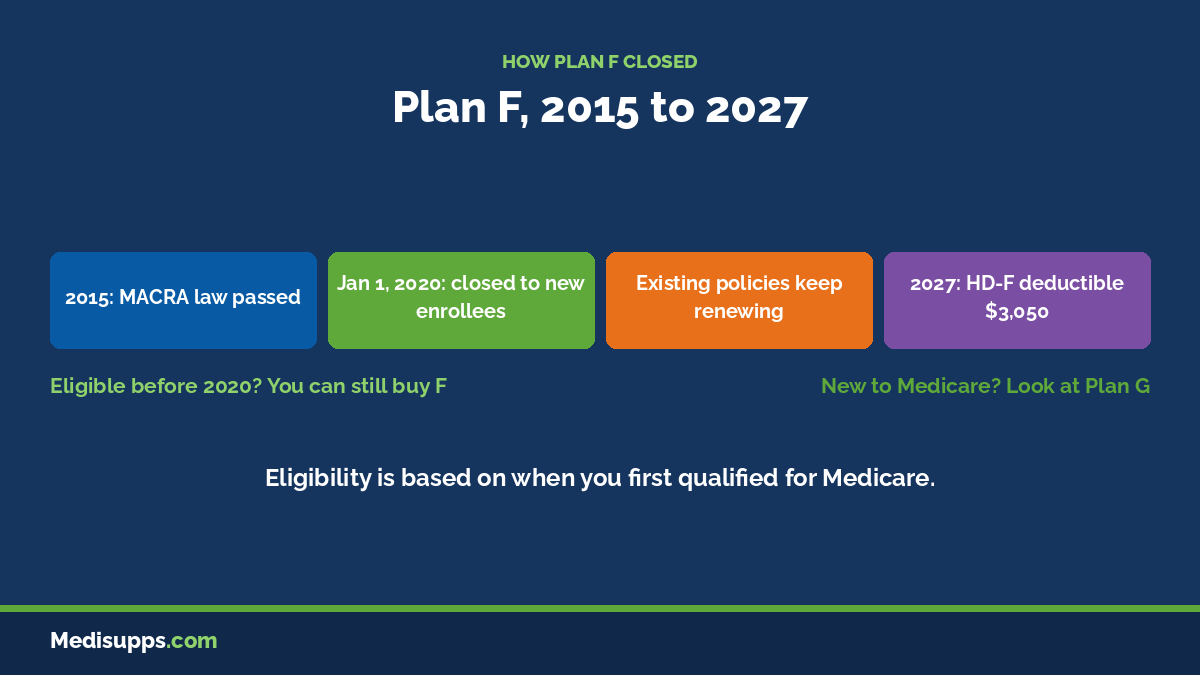
Section 401 of the Medicare Access and CHIP Reauthorization Act of 2015 stopped insurers from selling plans that cover the Part B deductible to anyone newly eligible for Medicare on or after January 1, 2020. That closed Plans C and F, and high-deductible F, to new enrollees. The key word is eligible, not enrolled.
- ✔You turned 65 before January 1, 2020, even if you delayed Part B because you kept working.
- ✔You qualified for Medicare through disability or kidney failure before 2020 and your state lets insurers sell Medigap to people under 65.
- ✔You already have Plan F and want to move it to another insurer, subject to that insurer’s health questions in most states.
Easy mistake
Someone born in 1954 who stayed on a large employer’s plan until 2027 is still Plan F eligible, because Medicare eligibility began at 65 in 2019. Someone born in 1955 is not, no matter when they enroll.
Plan F vs Plan G: The $292 Question
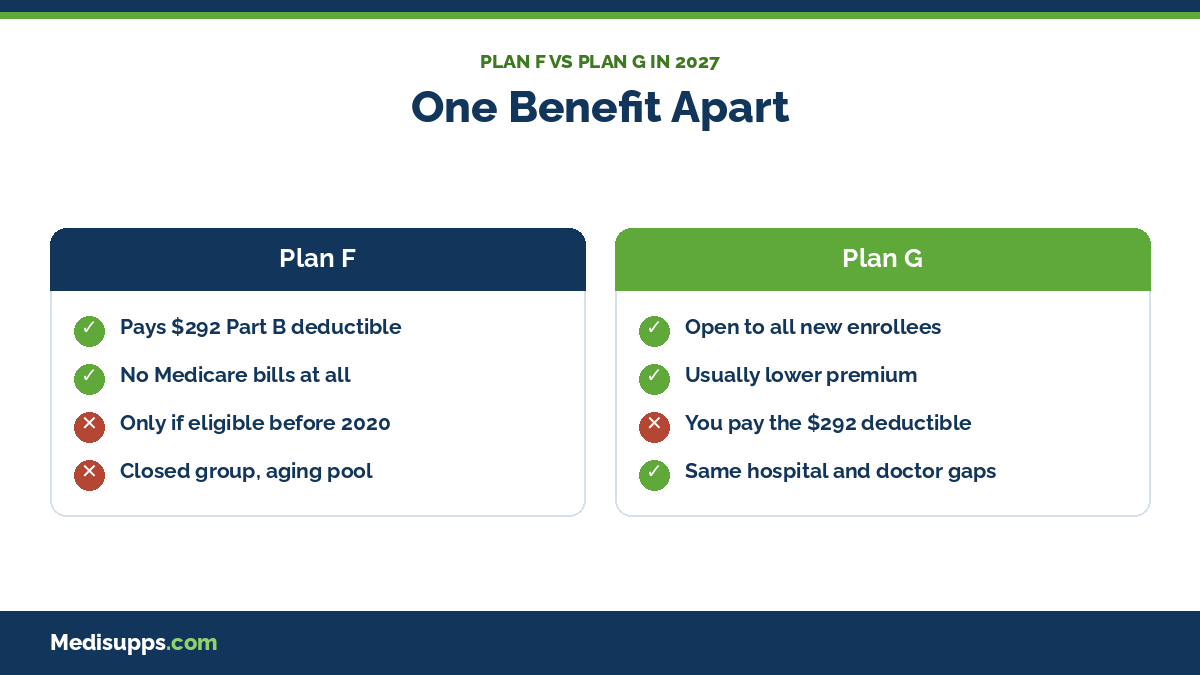
Plan G covers everything Plan F covers except the Part B deductible. So the comparison is simple: if Plan F costs more than $292 a year extra, which is $24.33 a month, Plan G leaves you ahead even after you pay the deductible yourself.
| Plan F premium is higher by | Extra cost per year | Minus 2027 Part B deductible | Plan G saves you |
|---|---|---|---|
| $15 a month | $180 | $292 | Nothing; F is $112 cheaper |
| $25 a month | $300 | $292 | $8 |
| $40 a month | $480 | $292 | $188 |
| $60 a month | $720 | $292 | $428 |
Illustrative premium gaps, not quotes. Check the actual Plan F and Plan G premiums for your age and ZIP code.
The rule of thumb
A Plan F premium that runs more than about $25 a month above Plan G at the same insurer makes Plan G the better buy, because the only benefit you give up is a fixed $292.
Our full Plan F vs Plan G comparison goes deeper into the differences.
Plan F Rate Review
Call a Licensed Agent Now
A licensed agent can compare your Plan F premium with Plan G from several insurers.
No obligation to enroll
Keeping Plan F or Switching to Plan G
In most states, moving from Plan F to Plan G after your first six months on Part B means answering health questions, and the new insurer can decline you. Never cancel Plan F until the Plan G policy is approved. Our guide on whether you can switch from Plan F to Plan G lists the common questions.

Eligibility check
A current Plan F policy stays in force as long as premiums are paid, even though the plan is closed to new enrollees. Canceling it before a replacement is approved can end the chance to buy Plan F again, because only people eligible for Medicare before 2020 qualify and most insurers ask health questions.
Russell Noga, Licensed Insurance Agent
Why a Closed Plan’s Premiums Can Climb Faster
Since 2020, no newly eligible 65-year-olds can join Plan F. Each insurer’s Plan F group, called a closed block, keeps getting older, and older policyholders tend to file more claims. Premiums are set for each group of policies, so a group with rising claims and no new members can see larger increases than an open plan like G. This is a general pattern, not a certainty, and it differs by insurer and state.
High-Deductible Plan F in 2027
High-deductible Plan F has the same benefits as Plan F once you have paid $3,050 in 2027 in costs Medicare does not cover. CMS sets that amount each year. It follows the same 2020 eligibility rule, and fewer insurers still sell it. People who can no longer buy it usually look at high-deductible Plan G, which uses the same deductible. Learn more about high-deductible Plan F, compare all Medicare Supplement plans, or return to the Medisupps.com home page.
Free premium review
See How Your Plan F Premium Stacks Up
Same benefits can cost much less at another insurance company.
Rates and plan availability vary by state, age and insurance company.
Plan F: Questions People Ask
➤ Is Medicare Supplement Plan F being discontinued?
No. Plan F is closed to people newly eligible on or after January 1, 2020, but insurers still renew existing Plan F policies and still sell them to people eligible before that date.
➤ Can I keep my Plan F if I move to another state?
Yes. Medigap policies are guaranteed renewable, so you can keep Plan F after a move as long as you pay the premium, although the premium may change to the rate for your new area.
➤ I turned 65 in 2019 but signed up for Medicare in 2026. Can I buy Plan F?
Generally yes. Eligibility depends on when you first became eligible for Medicare, not when you enrolled. Outside guaranteed issue periods, the insurer may still ask health questions.
➤ Why is Plan F more expensive than Plan G?
Plan F pays the Part B deductible, $292 in 2027, and its closed group of policyholders is getting older, which can push premiums up faster. Plan G leaves you that deductible.
➤ Does Plan F cover prescription drugs?
No. No Medigap plan sold today covers outpatient prescriptions. Plan F holders need a separate Part D plan to avoid a late enrollment penalty.
Medigap Quotes
Call a Licensed Agent Now
Find out whether the same coverage costs less with another company.
No obligation to enroll
Medisupps.com is operated by ZRN Health & Financial Services, LLC, a licensed insurance agency based in Austin, Texas. We are not connected with or endorsed by the U.S. government or the federal Medicare program. Premiums are examples only; your rate depends on your age, ZIP code, tobacco use and the insurance company.
Russell Noga is the CEO and Medicare editor of Medisupps.com. His 15 years of experience in the Medicare insurance market includes being a licensed Medicare insurance broker in all 50 states. He is frequently featured as a featured as a keynote Medicare event speaker, has authored hundreds of Medicare content pages, and hosts the very popular Medisupps.com Medicare Youtube channel. His expertise includes Medicare, Medigap insurance, Medicare Advantage plans, and Medicare Part D.