Medicare Plan G reviews for 2027 are really reviews of insurance companies, because every Plan G pays the same standardized benefits and leaves you only the $292 Part B deductible for Medicare-approved care. What separates a well-reviewed Plan G from a poorly reviewed one is the company’s financial strength, its complaint record, how fast it raises premiums and what it charges on day one.
Same benefits, different prices
Line Up Plan G Quotes From Several Companies
See which insurers price Plan G lowest for your age and ZIP code.
Rates and plan availability vary by state, age and insurance company.
Star ratings, testimonials and forum posts rarely capture those four things, so this guide shows where the numbers come from and how to read them: AM Best rating releases, state complaint indexes, a state rate-change report, and a state premium chart. For the plan itself, start with our Medicare Supplement Plan G guide. For every plan letter side by side, see Medicare Supplement plans for 2027.
Bottom line first
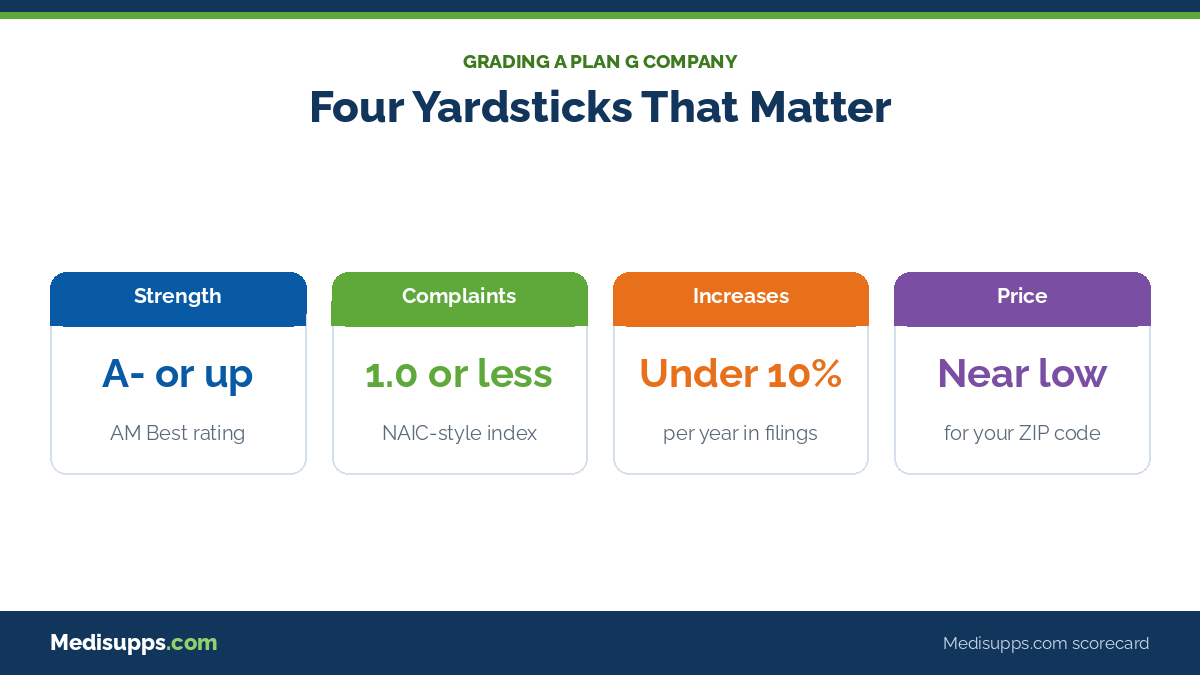
Plan G reviews in 2027 should grade the insurer, not the plan: check an AM Best rating of A- or better, a complaint index at or below the state average, single-digit yearly increases in your state’s rate filings, and a first-year premium near the low end for your ZIP code.
Why a Plan G Review Is Really a Company Review
Federal law fixes what Plan G pays. Whether the policy carries a household name or a small regional insurer’s logo, it covers the $1,776 Part A hospital deductible for 2027, Part A and Part B coinsurance, skilled nursing coinsurance of $222 a day for days 21 to 100, Part B excess charges, and 80% of emergency care abroad. You pay the $292 Part B deductible, then nothing more for Medicare-approved services.
That is why two Plan G policies can earn very different reviews. The same claim pays the same way, but the bill that arrives each month, and how it grows, depends entirely on the insurer.
The Four Yardsticks Worth Trusting
Skip these signals
Medicare star ratings apply to Medicare Advantage and Part D plans, not to supplements. Customer testimonials on an insurer’s own site are selected by the insurer. Neither tells you how a Plan G policy will be priced at 75.
Financial Strength: Recent AM Best Actions on Plan G Insurers
AM Best grades insurers from A++ (Superior) down through the B and C ranges. Anything from A- (Excellent) upward is a solid result for a Medigap carrier. The outlook attached to the rating matters too, because a negative outlook signals that a downgrade is possible.
| Insurer or group | AM Best rating | Latest action |
|---|---|---|
| Mutual of Omaha group (includes United World Life) | A+ (Superior), stable | Affirmed April 2026 |
| Physicians Mutual | A+ (Superior) | Upgraded from A, November 2025 |
| Aetna Health and Life group (includes Accendo) | A (Excellent), stable | Affirmed June 2026 |
| HCSC Medicare and Supplemental group (former Cigna Medigap) | A (Excellent), stable | Affirmed January 2026 |
| UnitedHealthcare health insurers | A (Excellent), stable | August 2026, down from A+ in March 2025 |
| New Era Life group | A- (Excellent), negative outlook | July 2026 |
Sources: AM Best rating releases on the dates shown. Ratings can change at any time; confirm the current rating for the exact company named on your application.
The UnitedHealthcare change shows why dates matter. AM Best tied weaker 2025 results to Medicare Advantage medical costs, not to supplements, yet a review written before August 2026 would still show the older A+ grade.

Before trusting a review
Match the rating and complaint data to the exact insurer printed on the application, not the brand on the brochure. Large groups file Medigap under several companies, and each one has its own complaint record and rate history in each state.
Russell Noga, Licensed Insurance Agent
How to Read a Complaint Index
A complaint index divides a company’s share of complaints by its share of premiums. Indiana’s 2025 health index, for example, sets the industry at 1.0: Anthem had 51 complaints on about $3.15 billion of premium, which works out to 0.83, below average. Missouri publishes the same idea on a 100-point scale for each line of business, including Medicare Supplement, so a score of 17 there means far fewer complaints than average.
Small companies can swing wildly: two complaints against a tiny block of policies can produce an index in the hundreds. Look at several years and at the Medicare Supplement line specifically, not the company’s whole health business.
| Company | NAIC-based complaint label in NerdWallet’s July 2026 Plan G review |
|---|---|
| State Farm | Far fewer complaints than expected |
| Mutual of Omaha | Far fewer complaints than expected |
| UnitedHealthcare | Fewer complaints than expected |
| HealthSpring (formerly Cigna) | Far more complaints than expected |
Source: NerdWallet, Best Medicare Supplement Plan G Companies, July 29, 2026, using NAIC complaint data.
Rate Increase History: The Review Score That Reaches Your Bank Account
Iowa’s Insurance Division publishes every Medigap rate change by company and policy form. Its November 2026 report shows how a single company’s increases can climb year after year. On UnitedHealthcare Insurance Company’s main Iowa group policy form, the changes ran about 8% in June 2023, about 15% in June 2024, mixed increases of 7% to 17% in June 2025, and 21.5% across the form in June 2026.
Our math
A premium of $200 a month that takes 8%, 15% and 21.5% increases in three straight years ends at about $302 a month, before any age-based increase. Two companies quoting the same $200 today can be $1,000 a year apart within three years.
Ask any company for its last three increases in your state before you apply, or check your state’s rate guide. Our Medigap rate increase history page explains where to find them.
Plan G Quotes
Call a Licensed Agent Now
Licensed agents compare Plan G premiums and rate histories from several insurers at no cost.
No obligation to enroll
Our 2027 Math: What a Year of Plan G Really Costs
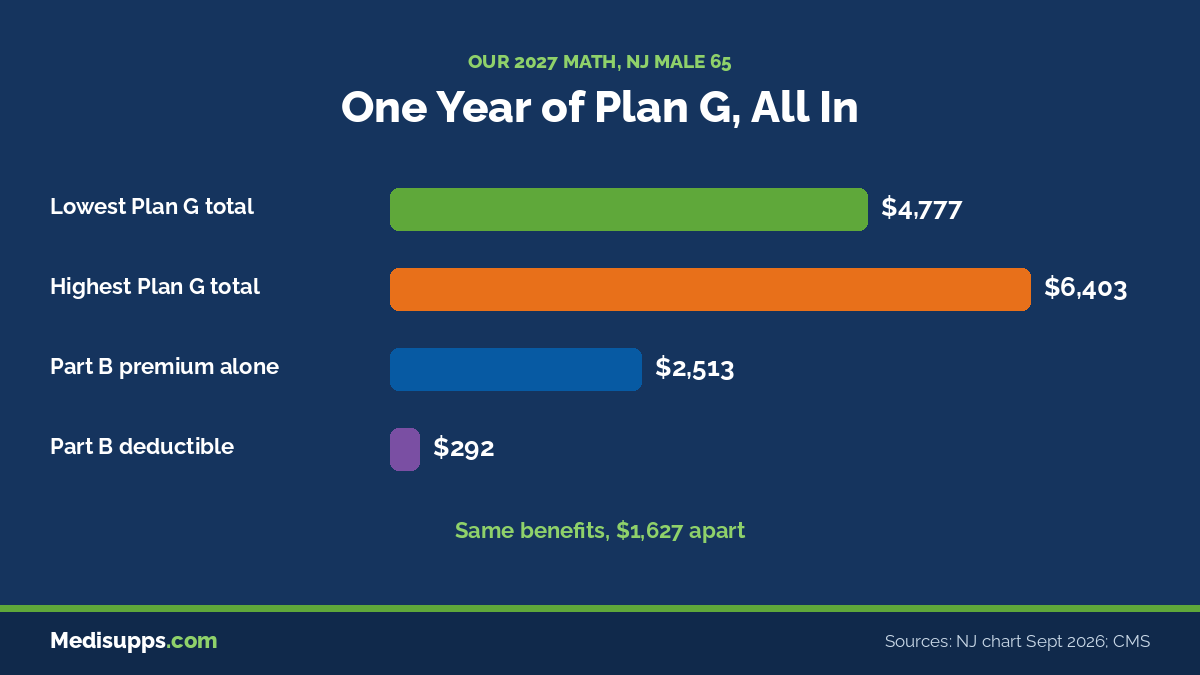
Reviews often quote a monthly premium and stop. The real yearly cost adds the Part B premium you pay Medicare and the Part B deductible Plan G does not cover. New Jersey’s September 2026 chart for a 65-year-old man shows how wide the gap can be for identical coverage.
| 2027 cost piece | Lowest Plan G on the NJ chart | Highest Plan G on the NJ chart |
|---|---|---|
| Plan G premium, 12 months | $1,971.72 ($164.31 a month) | $3,598.56 ($299.88 a month) |
| Part B premium ($209.40 a month) | $2,512.80 | $2,512.80 |
| Part B deductible | $292 | $292 |
| Total for a year with any Part B care | $4,776.52 | $6,403.36 |
Our math. Premiums: New Jersey Medigap chart, male age 65, preferred rates, September 2026 (lowest: Bankers Life, underwritten by Washington National; highest: Aetna Health Insurance Co.). 2027 Part B figures from CMS. Rates in 2027 may differ.
The two policies pay exactly the same claims, yet the higher one costs $1,626.84 more a year. Over a decade of rate increases, that gap usually widens rather than closes.
Turning Reviews Into a Decision
- ✔AM Best rating of A- or higher, with a stable outlook
- ✔Medicare Supplement complaint index at or below average for at least two recent years
- ✔No run of double-digit increases in your state’s last three filings
- ✔Premium within a modest range of the lowest quote in your ZIP code, after any household discount
- ✔A clear answer on whether the policy is issue-age, attained-age or community-rated
A company does not need to win every line. A slightly higher premium from an insurer with a steady filing history can be the cheaper policy by your mid-70s. Compare companies within our Medicare Supplement plans guides, browse the 2026 Medicare Supplement plans archive for last year’s carrier notes, or return to the Medisupps.com home page.
Free side-by-side
Check a Company’s Price and Track Record Before You Apply
Compare premiums from well-rated Medigap insurers in your state.
Rates and plan availability vary by state, age and insurance company.
Plan G Reviews: Questions Buyers Ask
➤ Do Plan G reviews matter if the benefits are identical?
Yes, because reviews that matter grade the insurer. Price, rate increases, complaints and financial strength differ by company even though the claims a Plan G pays do not.
➤ What is a good complaint index for a Medigap company?
On the NAIC scale, anything at or below 1.0 means the company draws no more complaints than expected for its size. On Missouri’s scale the average is 100. Check more than one year, since small companies swing widely.
➤ Why did UnitedHealthcare’s AM Best rating change?
In August 2026 AM Best rated UnitedHealthcare’s health insurers A (Excellent), down from A+ in March 2025, citing elevated Medicare Advantage medical costs in 2025. A is still an Excellent rating.
➤ Is the cheapest Plan G a red flag?
Not by itself. A low price paired with a weak rating or a run of large increases in state filings is the warning sign. A low price from a stable, well-rated company is simply a good deal.
➤ Where can I check a company’s Medigap complaints myself?
The NAIC Consumer Insurance Search tool lists complaint data by company, and some states, including Missouri, publish complaint indexes by line of business on their insurance department websites.
➤ Does a high AM Best rating keep my premium low?
No. The rating measures the ability to pay claims. A company rated A+ can still raise premiums faster than a company rated A-, so look at rate history separately.
Free Plan G Comparison
Call a Licensed Agent Now
Find the well-rated Plan G company with the lowest price for your ZIP code.
No obligation to enroll
Medisupps.com is operated by ZRN Health & Financial Services, LLC, a licensed insurance agency based in Austin, Texas. We are not connected with or endorsed by the U.S. government or the federal Medicare program. Premiums are examples only; your rate depends on your age, ZIP code, tobacco use and the insurance company.
Russell Noga is the CEO and Medicare editor of Medisupps.com. His 15 years of experience in the Medicare insurance market includes being a licensed Medicare insurance broker in all 50 states. He is frequently featured as a featured as a keynote Medicare event speaker, has authored hundreds of Medicare content pages, and hosts the very popular Medisupps.com Medicare Youtube channel. His expertise includes Medicare, Medigap insurance, Medicare Advantage plans, and Medicare Part D.