Yes, Medicare Plan G is still available in 2027 to anyone enrolled in Medicare Part A and Part B, no matter when they first became eligible, and no federal law has scheduled it to close. The plan that closed was Plan F, along with Plan C, and only for people who became eligible for Medicare on or after January 1, 2020.
Plan G in your state
Find Out Which Insurers Sell Plan G in Your ZIP Code
See current Plan G premiums side by side before you apply.
Rates and plan availability vary by state, age and insurance company.
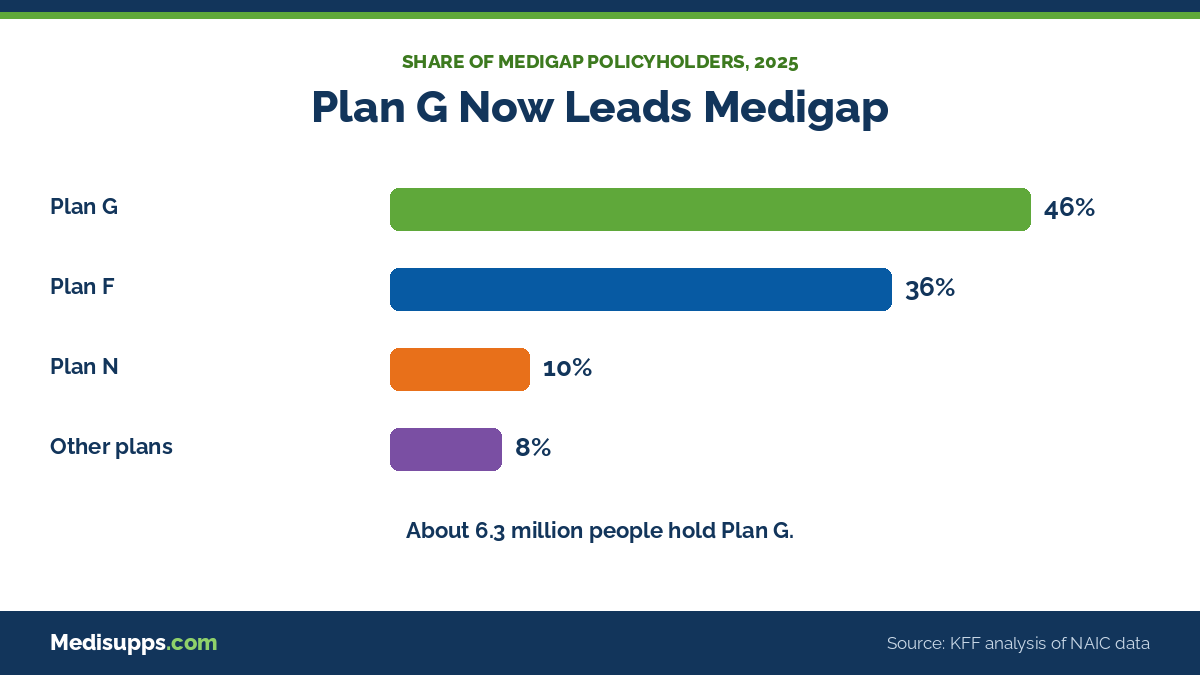
Plan G is now the most widely held Medigap plan in the country. KFF’s analysis of 2025 NAIC data counts about 6.3 million Plan G policyholders, 46% of everyone with a Medicare Supplement. Availability is not the same as easy access, though. Your state, your age and your timing decide whether an insurer must sell you Plan G or may turn you down. This page explains each case and points you to the rest of our Medicare Plan G guide.
Bottom line first
Plan G remains on sale in 2027 in every state that uses lettered Medigap plans. People new to Medicare can buy it; Plan F and Plan C are the plans closed to them.
Who Can Buy Plan G in 2027
Plan G is a standardized Medigap plan, so the benefits are fixed by federal law and identical from one insurer to the next. Whether you can actually get one depends on which group you fall into.
| Your situation | Can you buy Plan G? | Can an insurer say no? |
|---|---|---|
| Turning 65 in 2027, enrolled in Part B | Yes | No, during the six-month Medigap open enrollment period |
| Eligible for Medicare before 2020 | Yes, and Plan F is also open to you | Only outside open enrollment and guaranteed-issue situations |
| Already on Medicare, past open enrollment | Yes, if the insurer approves you | Yes, in most states, after health questions |
| Under 65 on Medicare due to disability | Depends on your state | Often, unless state law requires a sale |
| Living in Massachusetts, Minnesota or Wisconsin | Not under the Plan G name | Those states use their own standardized plans |
Rules summarized from federal Medigap law and state requirements; check your state’s insurance department for details.
Why Plan F Closed and Plan G Did Not
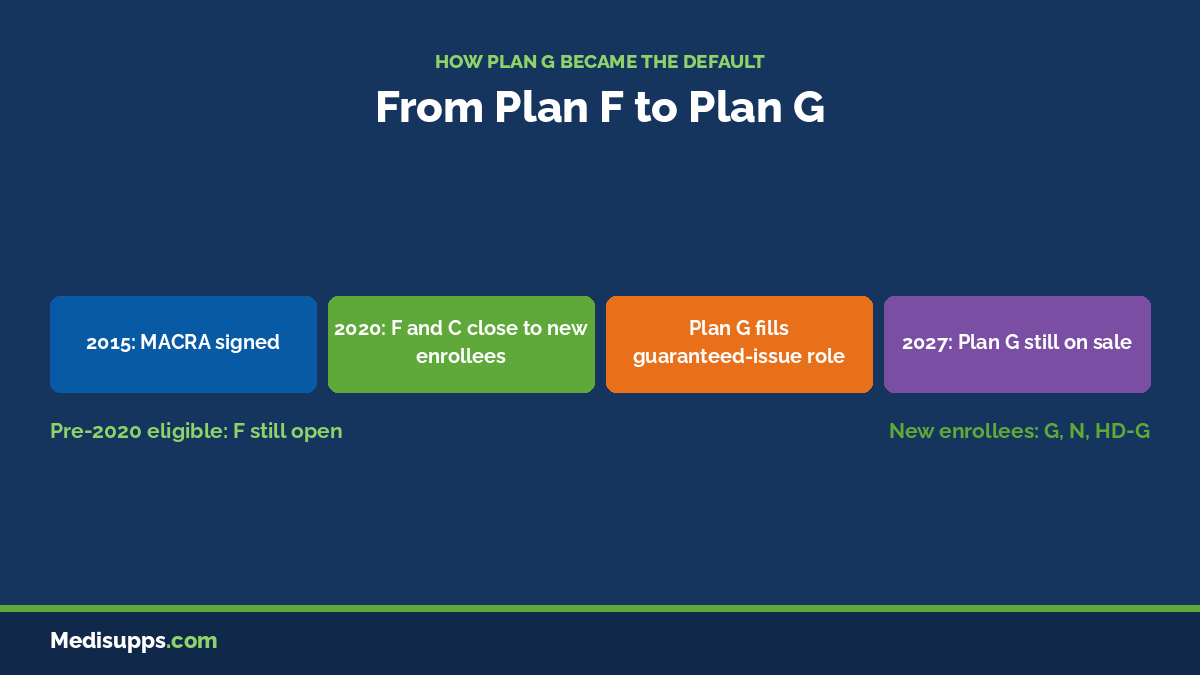
The Medicare Access and CHIP Reauthorization Act of 2015, known as MACRA, barred insurers from selling Medigap plans that pay the Part B deductible to anyone newly eligible for Medicare on or after January 1, 2020. Plan C and Plan F were the only plans that paid it, so they were the only plans affected. Plan G pays everything Plan F pays except that deductible, which is $292 in 2027.
The whole difference
Plan G covers the Part A deductible ($1,776 in 2027), Part A and B coinsurance, skilled nursing coinsurance, Part B excess charges and foreign travel emergencies. You pay the $292 Part B deductible yourself once a year.
People who were eligible before 2020 can still buy Plan F, even if they delayed enrolling. For them, Plan G is usually cheaper whenever the yearly premium gap between F and G is larger than $292. Our page on Medicare Supplement Plan F covers who still qualifies.
Plan G Took Plan F’s Place in Guaranteed-Issue Rules
Federal guaranteed-issue rights let you buy certain Medigap plans without health questions in specific situations, such as losing employer retiree coverage or leaving a Medicare Advantage plan during a first-year trial. Many of those rules were written before 2020 and named Plan C or Plan F.
Little-known MACRA rule
For anyone newly eligible from January 1, 2020 on, MACRA treats every reference to Plan C or Plan F as a reference to Plan D or Plan G. The NAIC’s producer bulletin on the change states that the required offer for these people is Plan D or Plan G, not C or F. So when a guaranteed-issue right applies, Plan G is the most complete plan you can claim.
- ✔Your employer or union group coverage that pays after Medicare is ending.
- ✔You joined a Medicare Advantage plan when first eligible at 65 and leave it within the first 12 months.
- ✔Your Medicare Advantage plan leaves Medicare or stops serving your area.
- ✔Your Medigap insurer goes bankrupt or misled you.

Worth checking first
Plan G is available, but approval is not automatic after open enrollment ends. Anyone switching from Plan F to Plan G, or from Medicare Advantage back to Original Medicare, should confirm whether a guaranteed-issue right or state rule applies before canceling current coverage.
Russell Noga, Licensed Insurance Agent
Where Plan G Is Harder to Get
Plan G is sold everywhere lettered plans exist, but four situations make it harder to buy at a fair price.
A handful of states loosen the first barrier. KFF reports that Connecticut, Maine, Massachusetts and New York require some form of continuous or annual guaranteed issue for people 65 and older, and Minnesota adds an annual window for ages 65 to 70 starting August 2026.
Plan G Quotes
Call a Licensed Agent Now
Licensed agents check which insurers sell Plan G where you live and compare their rates at no cost.
No obligation to enroll
Plan G Comes in Two Versions for 2027
The high-deductible version is also open to people new to Medicare, unlike high-deductible Plan F. It suits healthy people who can absorb a bad year. Read more about high-deductible Plan G before you choose it.
Will Plan G Ever Go Away?
No federal law ends Plan G sales. Congress closed Plan F to new enrollees for one reason: to stop first-dollar coverage of the Part B deductible. Plan G already leaves that deductible to you, so MACRA does not reach it.
To compare Plan G with every other letter, see our Medicare Supplement plans for 2027, browse all Medicare Supplement plans, or get started on the Medisupps.com home page.
Free quote
Lock In Plan G While Your Enrollment Window Is Open
Compare insurers now, while no health questions can be asked.
Rates and plan availability vary by state, age and insurance company.
Plan G Availability: Questions People Ask
➤ Can I buy Plan G if I turned 65 after 2020?
Yes. Plan G is open to people who became eligible for Medicare on or after January 1, 2020. Only Plan C and Plan F are closed to that group.
➤ Is Plan G being discontinued like Plan F?
No. The 2015 MACRA law closed only plans that pay the Part B deductible. Plan G does not pay it, so the law does not affect Plan G.
➤ Can I get Plan G with a guaranteed-issue right?
Yes. For people newly eligible since 2020, federal rules that once named Plan C or F now point to Plan D or G, so Plan G is available when a guaranteed-issue right applies.
➤ How many people have Plan G?
KFF’s analysis of 2025 NAIC data shows about 6.3 million Plan G policyholders, 46% of all Medigap enrollees, ahead of Plan F at 36% and Plan N at 10%.
➤ Can I buy Plan G in Massachusetts, Minnesota or Wisconsin?
Not by that letter. Those three states use their own standardized Medigap designs, with similar basic and optional benefits sold under different names.
➤ Can an insurer refuse to sell me Plan G?
Outside your open enrollment period and guaranteed-issue situations, yes, in most states. Insurers can use health questions to decline you or charge a higher rate.
➤ Is high-deductible Plan G still available?
Yes, where insurers file it. In 2027 you pay the first $3,050 of covered costs before the plan pays in full.
Plan G Availability Check
Call a Licensed Agent Now
Find out whether you can buy Plan G without health questions and what it costs.
No obligation to enroll
Medisupps.com is operated by ZRN Health & Financial Services, LLC, a licensed insurance agency based in Austin, Texas. We are not connected with or endorsed by the U.S. government or the federal Medicare program. Premiums are examples only; your rate depends on your age, ZIP code, tobacco use and the insurance company.
Russell Noga is the CEO and Medicare editor of Medisupps.com. His 15 years of experience in the Medicare insurance market includes being a licensed Medicare insurance broker in all 50 states. He is frequently featured as a featured as a keynote Medicare event speaker, has authored hundreds of Medicare content pages, and hosts the very popular Medisupps.com Medicare Youtube channel. His expertise includes Medicare, Medigap insurance, Medicare Advantage plans, and Medicare Part D.