by Russell Noga | Updated October 6th, 2026
Aetna is one of the best-known names in health insurance, and its Medicare Supplement plans help pay the costs Original Medicare leaves behind. Plan G and Plan N are its most popular choices for 2027, with high-deductible Plan G as a lower-premium option.
Below we cover what each Aetna plan pays, how Plan G and Plan N compare, the new 2027 deductibles, Aetna’s household discount and when you can enroll. For every company and plan side by side, see our guide to Medicare Supplement Plans for 2027.
Key Takeaway
Aetna sells standardized Medigap plans, so a Plan G from Aetna covers exactly what a Plan G from any other company covers. What changes from company to company is the premium, the household discount and the rate increase history, so compare Aetna’s price against other top companies before you buy.
Aetna Medicare Supplement at a glance

Why Choose an Aetna Medicare Supplement?
Medicare Supplement plans are standardized plans sold by private insurance companies, so the coverage is the same no matter which company you choose. Aetna’s appeal comes down to the company behind the policy and the price in your area.
Any Doctor That Takes Medicare
Unlike Medicare Advantage, Medicare Supplement plans let you see any doctor, specialist or hospital in the country that accepts Medicare.
No Networks or Referrals
Aetna’s Medigap plans do not add their own networks, referrals or prior authorization rules on top of Medicare.
Guaranteed Renewable
As long as you pay your premium, Aetna cannot cancel your policy because of your health or age.
Aetna Medigap Plan Options for 2027
There are ten standardized Medicare Supplement plans. Aetna sells a smaller lineup that varies by state, issued through affiliated companies such as Aetna Health and Life Insurance Company, Continental Life Insurance Company of Brentwood, Tennessee, and Accendo Insurance Company. Here is what each Aetna plan leaves you to pay:
| Aetna Plan | Who Can Buy It | What You Still Pay |
|---|---|---|
| Plan G | Anyone with Medicare Parts A and B | Only the Part B deductible ($283 in 2026) |
| Plan N | Anyone with Medicare Parts A and B | Part B deductible, copays up to $20 for some office visits and up to $50 for some ER visits, and Part B excess charges |
| High-Deductible Plan G | Anyone with Medicare Parts A and B | Medicare-covered costs up to $3,050 in 2027, then nothing |
| Plan A | Anyone with Medicare Parts A and B | Part A and Part B deductibles, skilled nursing coinsurance, excess charges and foreign travel care |
| Plan B | Anyone with Medicare Parts A and B | Part B deductible, skilled nursing coinsurance, excess charges and foreign travel care |
| Plan F and High-Deductible F | Only people eligible for Medicare before January 1, 2020 | Nothing with Plan F; up to $3,050 in 2027 with High-Deductible F |
Plan availability varies by state and by Aetna company. Massachusetts, Minnesota and Wisconsin use their own standardized plans.
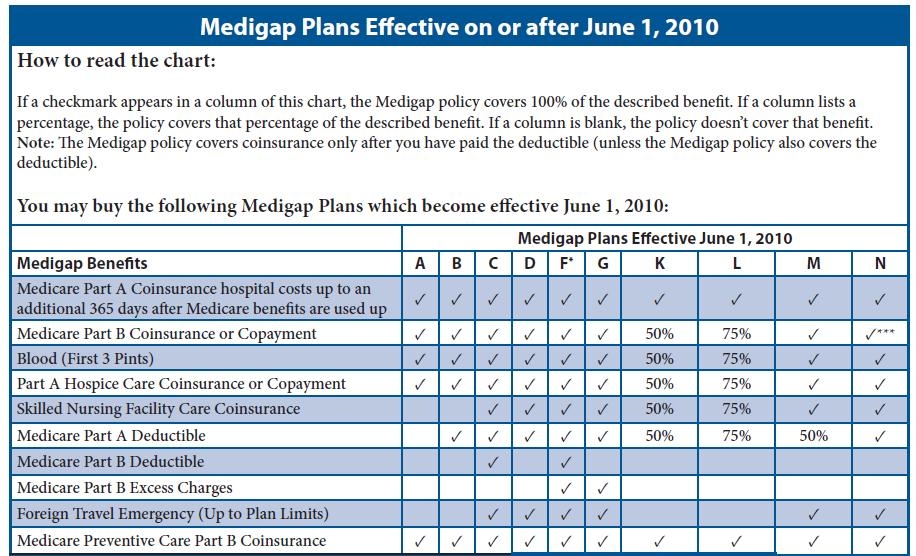
Aetna Plan F covers everything, including both Medicare deductibles, but only if you were eligible for Medicare before 2020. See every plan letter side by side on our Medicare Supplement plans comparison chart for 2027.
2027 Medicare Numbers That Affect Your Aetna Plan
Medigap benefits are set by federal law, but the dollar amounts they work around change every year:
| Medicare Cost | 2026 | 2027 |
|---|---|---|
| Part B deductible (what Plan G and N leave you) | $283 | About $292 projected; final amount announced in November |
| High-deductible Plan G and F deductible | $2,950 | $3,050 |
| Part A hospital deductible (covered by Plan G and N) | $1,736 | Announced in November |
| Part D drug deductible (separate drug plan) | Up to $615 | Up to $700 |
| Part D out-of-pocket cap | $2,100 | $2,400 |
Sources: CMS 2027 Medigap high-deductible announcement, CMS 2027 Part D parameters and the 2026 Medicare Trustees Report projection for the Part B deductible.
Same plan, same benefits: Every company’s Plan G pays the same benefits, so Aetna’s Plan G and another company’s Plan G only differ in price, discounts and customer service.
Aetna Medicare Plan G: The Top Plan for 2027
Medicare Plan G is the most popular Aetna Medicare Supplement plan for people new to Medicare. Once you pay the annual Part B deductible, Plan G covers 100% of your remaining Medicare-approved costs for the year.
What Aetna Plan G Covers
Aetna Medicare Supplement Plan G pays the costs Medicare Part A and Part B leave behind, including:
Good to know: Plan G does not cover the Part B deductible, which is $283 in 2026 and projected at about $292 for 2027. For most people that trade is worth it, because Plan G’s premium is usually far lower than Plan F’s for nearly the same coverage.
Aetna Plan G Rates
Aetna’s Plan G premium depends on your age, ZIP code, gender, tobacco use and whether you qualify for a household discount. Prices for the exact same Plan G can differ by a wide margin between companies in the same ZIP code, so use our FREE quote engine to see Aetna’s rate next to other top companies in your area.
Aetna Medicare Plan N: Lower Premium, Small Copays
Aetna Medicare Plan N is the second most popular choice, built for people who want a lower premium without giving up much coverage. Medicare Supplement Plan N covers most of the same costs as Plan G but asks you to pay a few small copays.
What Aetna Plan N Covers
Watch for
Plan N does not cover the Part B deductible, copays of up to $20 for some office visits, copays of up to $50 for ER visits that do not end in admission, or Medicare Part B excess charges of up to 15% above the Medicare-approved amount. Most doctors accept Medicare assignment and never bill excess charges.
Aetna Plan N Rates
Plan N premiums are usually lower than Plan G premiums. Depending on your age and location, the yearly premium savings can be enough to cover several doctor copays, which makes Plan N a strong value if you are healthy and see the doctor a few times a year.
Aetna Plan G vs Plan N
The choice between Aetna Plan G and Plan N comes down to two coverage differences and the premium gap in your ZIP code.
| Feature | Aetna Plan G | Aetna Plan N |
|---|---|---|
| Part B deductible | You pay it | You pay it |
| Office visit copays | None | Up to $20 for some visits |
| ER copays | None | Up to $50 if not admitted |
| Part B excess charges | Covered | Not covered |
| Premium | Higher | Lower |
Both plans cover the Part A deductible, hospital and skilled nursing coinsurance, blood and foreign travel emergency care.
Plan G fits if you
Plan N fits if you
When comparing premiums, weigh Plan G’s extra coverage against Plan N’s yearly savings. Aetna is competitive in many areas, and other strong companies include Mutual of Omaha, Allstate and Manhattan Life.
Aetna High-Deductible Plan G
Aetna also sells high-deductible Plan G in many states. It has the same benefits as regular Plan G, but you pay Medicare-covered costs up to a yearly deductible before the plan starts paying. In exchange, the premium is much lower.
$3,050
$2,950
100% covered
High-deductible Plan G can fit people who are healthy, have savings set aside and mainly want protection against a large hospital bill. Your Part B deductible counts toward the $3,050.
Is Aetna Plan F Worth Considering?
Aetna Plan F covers everything, including the Part B deductible, but federal law closed it to anyone who became eligible for Medicare on or after January 1, 2020. Because no new enrollees are joining, Plan F premiums often rise faster than Plan G premiums.
Already on Plan F? Plan G covers everything Plan F does except the Part B deductible. If the yearly premium savings are bigger than the deductible, switching to Plan G can save you money, as long as you can pass health questions or have a right to switch.
Aetna Household Discount
In many states, Aetna gives a household premium discount when you live with another adult, such as a spouse, partner or roommate. The discount is commonly 7%, and Accendo policies have offered up to 14% in select states. Rules and amounts vary by state, so a licensed agent can confirm whether you qualify at your ZIP code.
When to Enroll in an Aetna Medicare Supplement Plan
The best time to buy is your 6-month Medigap Open Enrollment Period. It starts the first day of the month you are both 65 or older and enrolled in Medicare Part B. During those six months, Aetna must accept you and cannot charge more because of your health.

Good to know: The October 15 to December 7 Annual Enrollment Period is for Medicare Advantage and Part D. It does not give you a right to switch Medicare Supplement plans without health questions.
If you are over 65 and still have employer coverage, you may be able to delay Part B. Your Medigap Open Enrollment Period then starts when you enroll in Part B, so you keep this protection for later.
Losing Your Medicare Advantage Plan in 2027?
Several large carriers are dropping Medicare Advantage plans and counties for 2027. If your plan is leaving Medicare or no longer serves your area, federal law generally gives you a guaranteed issue right to buy certain Medigap plans, which for most people include Plan G, with no health questions.
Guaranteed Renewability
Aetna’s Medicare Supplement plans are guaranteed renewable. Your policy stays in force as long as you pay your premium on time, and Aetna cannot cancel it because of changes in your health.
How to Choose an Aetna Medicare Supplement Plan

The Bottom Line
Aetna Plan G gives the most complete coverage for new enrollees, Plan N trades small copays for a lower premium, and high-deductible Plan G keeps premiums low with a $3,050 deductible in 2027. Because the benefits are standardized, the right Aetna plan is the one with the best price for your needs. Compare Aetna with other top companies on this page or call 1-888-891-0229.
Frequently Asked Questions
➤ What are Aetna Medicare Supplement plans?
Aetna Medicare Supplement plans, also called Medigap, are policies from Aetna and its affiliated insurance companies that work alongside Original Medicare. They pay some or all of the deductibles, coinsurance and copays Medicare leaves behind, depending on the plan letter you choose.
➤ Which Aetna Medicare Supplement plans are available in 2027?
Aetna’s lineup varies by state and may include Plans A, B, F, G, high-deductible G and N, plus high-deductible F for people eligible for Medicare before 2020. Plan G and Plan N are the most popular, and a licensed agent can confirm which plans Aetna sells at your ZIP code.
➤ Is Aetna Plan G or Plan N better?
Plan G covers more, leaving you only the Part B deductible, while Plan N has a lower premium but adds small copays and does not cover Part B excess charges. Plan G usually fits people who see doctors often or want predictable costs, and Plan N fits healthy people who want to save on premiums.
➤ What is the Aetna high-deductible Plan G deductible for 2027?
CMS set the 2027 deductible for high-deductible Plans F and G at $3,050, up from $2,950 in 2026. You pay Medicare-covered costs up to that amount before the plan pays, and then it covers the rest of the year like regular Plan G.
➤ Does Aetna offer a household discount?
In many states, yes. Aetna’s household discount is commonly 7%, and Accendo policies have offered up to 14% in select states, but eligibility rules and amounts vary by state.
➤ Can I see any doctor with an Aetna Medicare Supplement plan?
Yes. You can see any doctor or hospital in the U.S. that accepts Medicare, with no network, no referrals and no extra prior authorization from Aetna.
➤ Do Aetna Medicare Supplement plans cover prescription drugs?
No. Medigap plans sold since 2006 do not include drug coverage, so you need a separate Medicare Part D plan. For 2027, the Part D deductible can be up to $700 and out-of-pocket drug costs are capped at $2,400.
➤ When can I enroll in an Aetna Medicare Supplement plan?
You can apply any time of year, but the best time is your 6-month Medigap Open Enrollment Period, when Aetna cannot turn you down or charge more because of your health. Outside that window, you may need to answer health questions unless you have a guaranteed issue right, such as losing a Medicare Advantage plan.
➤ Can I switch to Aetna from another Medicare Supplement company?
Usually yes, but in most states you will answer health questions and Aetna can decline you based on your answers. Some states have birthday or anniversary rules that give you a yearly window to switch to a plan with equal or lesser benefits without health questions.
➤ How do I get Aetna Medicare Supplement rates?
Enter your ZIP code in the quote tool on this page to see Aetna rates next to other top companies in your area. You can also call 1-888-891-0229 and a licensed agent will compare plans and help with the application at no cost.
Russell Noga is the CEO and Medicare editor of Medisupps.com. His 15 years of experience in the Medicare insurance market includes being a licensed Medicare insurance broker in all 50 states. He is frequently featured as a featured as a keynote Medicare event speaker, has authored hundreds of Medicare content pages, and hosts the very popular Medisupps.com Medicare Youtube channel. His expertise includes Medicare, Medigap insurance, Medicare Advantage plans, and Medicare Part D.